Your Trusted Houston Commercial Real Estate Brokerage
Viking Enterprise LLC is part of eXp Commercial, an agent-led, cloud-based commercial real estate brokerage with agents across the globe.
Email: [email protected]
Call: (281) 222-0433
Your Trusted Katy / Fulshear & Houston Commercial Real Estate Brokerage
Viking Enterprise LLC is part of eXp Commercial, an agent-led, cloud-based commercial real estate brokerage with agents across the globe.
Looking to invest, buy, sell or lease? We can help.
Looking to invest, buy, sell or lease? We can help.
FEATURED PROPERTIES
OUR FEATURED TENANTS & CLIENTS
eXp Commercial - Viking Enterprise Team's real estate network provides unparalleled commercial real estate services to Tenants and Landlords around the Katy- Houston area. Our knowledge, experience, and reputation sets us apart from many firms.
A commercial property owner might have various plans that would necessitate the services of a commercial real estate broker. Some of the common scenarios include:
1. Selling the Property: If the owner decides it’s time to sell the property, a commercial real estate broker can help determine the market value, market the property effectively, and negotiate with potential buyers to get the best possible price.
2. Leasing Space: For property owners looking to lease out part or all of their commercial space, a broker can help find suitable tenants, negotiate lease terms, and ensure the lease agreements meet all legal requirements and serve the owner’s best interests.
3. Acquiring More Properties: Owners looking to expand their portfolio would benefit from a broker's knowledge of the market, access to listings, and negotiation skills to secure additional properties at favorable terms.
4. Property Management: While not all brokers offer this service, some commercial real estate brokers or their affiliates offer property management services. This can be particularly appealing for owners who prefer a hands-off approach or are managing properties from a distance.
5. Market Analysis: Owners considering future developments, renovations, or rebranding of their property might engage a broker for a comprehensive market analysis. This helps in understanding current market trends, the demand for different types of spaces, and potential returns on investment for various strategies.
6. Refinancing: In situations where a property owner is looking to refinance their property, a commercial real estate broker can provide valuable insights into the property’s current market value, assist in gathering necessary documentation, and even help in finding the best financing options.
7. Partnership or Investment Opportunities: Owners interested in exploring partnerships, joint ventures, or seeking investors for expansion or development projects might use a broker to find and vet potential partners or investors.
8. Consulting on Zoning and Use Changes: When contemplating a change in the use of the property or dealing with zoning issues, a broker with experience in local regulations and the specific property type can provide guidance and strategic planning assistance.
9. Exit Strategy Planning: For owners looking to plan an exit strategy from their investment, whether it’s through a strategic sale or a gradual winding down of operations, brokers can provide market insights, timing advice, and valuation services to optimize the exit process.
In any of these scenarios, the expertise and services provided by a commercial real estate broker can save the property owner time and money, while also providing access to a wider network of potential buyers, tenants, and industry professionals. Give us a call today!
Reviews
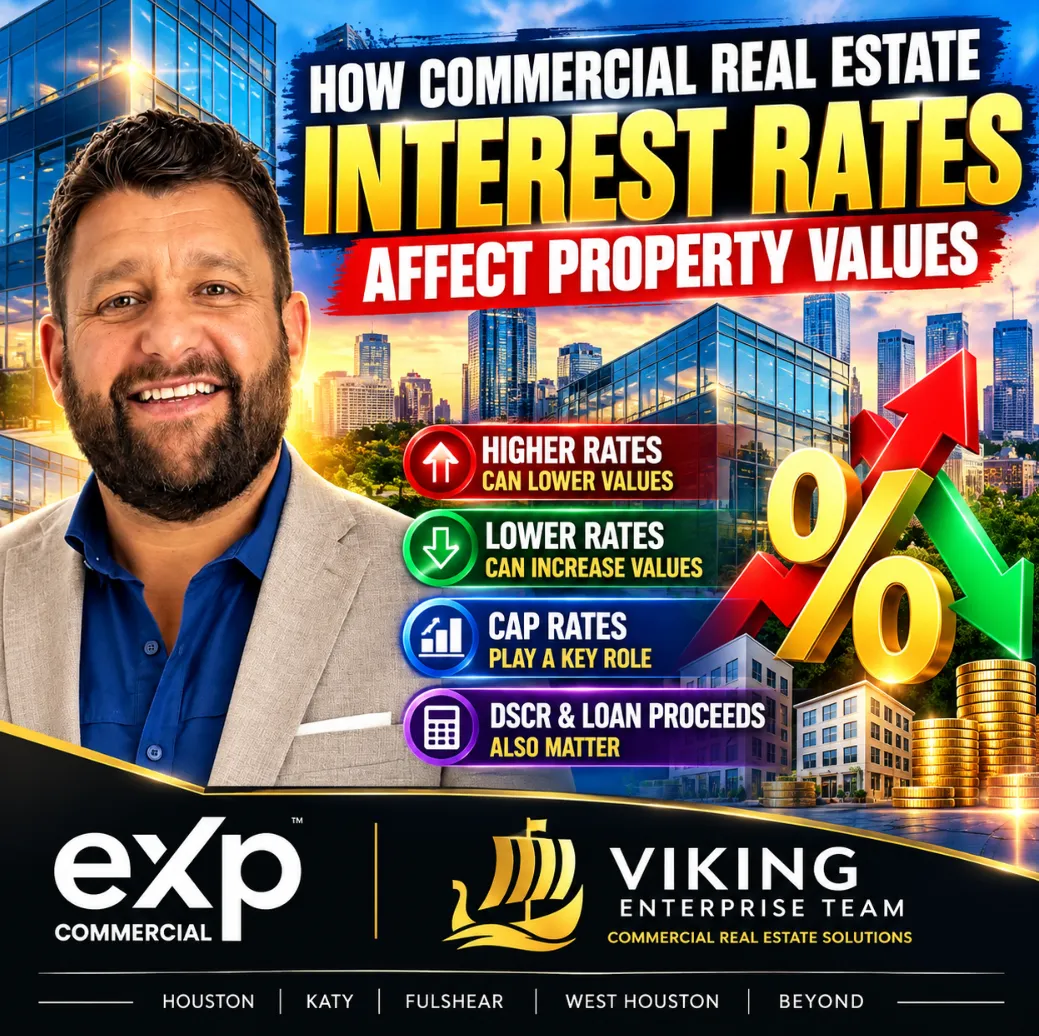
🏢 How Commercial Real Estate Interest Rates Affect Property Values: What Investors Need to Know 📈
🏢 How Commercial Real Estate Interest Rates Affect Property Values: What Investors Need to Know 📈
💰 Interest Rates vs. Commercial Property Values: Why Higher Rates Can Push CRE Prices Down 🏙️
________________________________________________________________________________
How Commercial Real Estate Interest Rates Affect Property Values
Interest rates are one of the most important forces influencing commercial real estate values. When rates move, the impact extends far beyond the monthly mortgage payment.
Higher borrowing costs can reduce investor returns, constrain loan proceeds, influence cap rates, and ultimately change what buyers are willing—or able—to pay for a property.
But the relationship is not as simple as rates go up, property values go down.
Net operating income, rent growth, supply and demand, occupancy, investor expectations, lender underwriting, and the availability of capital all play a role.
For commercial real estate investors and business owners, understanding these relationships can help you make better acquisition, disposition, refinancing, and financing decisions.
Why Interest Rates Matter in Commercial Real Estate
Most commercial real estate transactions involve leverage.
If an investor purchases a $5 million property, they may finance 60% to 75% of the acquisition. When the interest rate on that debt increases, the property's annual debt service generally increases as well.
That can create several consequences:
·Lower cash flow after debt service
·Lower cash-on-cash returns
·Reduced debt-service coverage
·Lower maximum loan proceeds
·Greater equity requirements
·Pressure on the price a leveraged buyer can afford to pay
This is why financing conditions and property valuations are closely connected.
The Connection Between Interest Rates and Cap Rates
Commercial real estate is frequently valued using the capitalization rate:
Property Value = Net Operating Income ÷ Cap Rate
Assume a property produces $500,000 of annual NOI.
At a 5% cap rate, the indicated value is:
$500,000 ÷ 5% = $10,000,000
At a 6% cap rate, the indicated value becomes:
$500,000 ÷ 6% = $8,333,333
At a 7% cap rate, it falls to approximately:
$500,000 ÷ 7% = $7,142,857
That illustrates why relatively small changes in cap rates can create significant changes in property valuations.
Interest rates and cap rates do not move in perfect lockstep, but higher borrowing costs can contribute to upward pressure on cap rates as investors demand sufficient returns relative to their cost of capital and alternative investments.
Higher Rates Can Reduce Loan Proceeds
One of the most overlooked effects of higher interest rates is their impact on commercial loan sizing.
A lender might advertise a maximum 70% loan-to-value ratio, but that does not automatically mean a borrower will receive 70% financing.
Commercial loans can also be constrained by debt-service coverage ratio (DSCR) and debt yield requirements.
When interest rates rise, the same loan amount produces higher debt service. If NOI does not increase sufficiently, the property's DSCR declines.
The lender may therefore reduce the loan amount.
That means an investor who expected 30% equity could suddenly need 35%, 40%, or more.
Why Buyers May Lower Their Offers
Consider a buyer evaluating a commercial investment.
If financing becomes more expensive while rents and NOI remain unchanged, the buyer may face a lower leveraged return.
The buyer essentially has several choices:
Pay more equity.
Accept a lower return.
Obtain better financing.
Increase the property's income.
Pay a lower purchase price.
That final option is one reason higher rates can place downward pressure on commercial property values.
The Refinancing Problem
Interest rates also affect owners who are not selling.
Commercial real estate loans commonly have maturities that are shorter than their amortization periods. An investor could have a loan amortized over 25 years but maturing after five, seven, or ten years.
At maturity, the remaining balance generally needs to be refinanced or paid off.
Suppose an owner financed a property when rates were substantially lower. When the loan matures, the replacement loan could have significantly higher debt service.
The property may no longer support the same loan balance under the lender's DSCR requirements.
This can create a refinancing gap.
The owner may need to contribute additional equity, restructure the financing, improve NOI, extend the existing debt, or sell the property.
Interest Rates Are Only Part of the Valuation Equation
A common mistake is assuming interest rates alone determine commercial property values.
They do not.
Consider a property where rents are increasing rapidly and occupancy is strong. NOI could increase enough to partially or fully offset cap-rate expansion.
For example, a property generating $500,000 of NOI at a 5% cap rate is worth $10 million.
If NOI grows to $600,000 and the market cap rate expands to 6%, the indicated value is still:
$600,000 ÷ 6% = $10,000,000
The cap rate increased, but the higher income offset the impact.
This is why investors should focus on both sides of the equation: income and valuation multiples.
Not Every Property Type Reacts the Same Way
Interest-rate sensitivity can also differ across property types and markets.
A fully leased industrial property with strong rent growth and a credit tenant may respond differently than an older office building with substantial vacancy.
Similarly, a well-located retail center with below-market rents could offer significant NOI growth potential despite a higher-rate environment.
Investors should evaluate factors such as tenant credit, lease rollover, rent growth, vacancy, capital expenditures, market supply, replacement cost, location, and future NOI—not rates alone.
Higher Interest Rates Can Create Opportunities
Higher rates are not automatically bad for commercial real estate investors.
They can reduce competition from highly leveraged buyers and create opportunities for investors with available capital.
A higher-rate environment may also produce:
·More motivated sellers
·Better acquisition pricing
·Seller-financing opportunities
·Assumable debt opportunities
·Preferred-equity structures
·Value-add acquisitions
·Refinancing opportunities when rates eventually improve
The key is underwriting the investment based on realistic financing assumptions rather than assuming yesterday's capital markets will return tomorrow.
What Investors Should Stress-Test
Before acquiring or refinancing commercial real estate, investors should model multiple scenarios.
Instead of asking only, “What is my interest rate today?”, ask what happens if the property's financial assumptions change.
For example:
What happens if the refinance rate is 1% or 2% higher?
What happens if the lender requires a higher DSCR?
What happens if the exit cap rate increases?
What happens if NOI falls 10%?
What happens if the property requires more equity at refinancing?
Sophisticated underwriting should consider both the property risk and capital-market risk.
What Business Owners Should Know
Interest rates matter for owner-occupied commercial real estate as well.
A business purchasing an office, warehouse, medical facility, retail property, or other operating location should evaluate more than the purchase price.
Financing structure can materially affect occupancy costs and cash flow.
Depending on the transaction, conventional commercial financing, SBA financing, construction financing, or other structures may produce very different results.
The right question is not simply:
“What is the lowest rate?”
It is:
“Which financing and real estate structure best supports the business?”
The Bottom Line
Commercial real estate interest rates can affect property values through several channels simultaneously.
Higher rates can increase debt service, reduce DSCR, constrain loan proceeds, increase required equity, lower leveraged returns, and put upward pressure on cap rates.
But interest rates do not determine value in isolation.
NOI, rent growth, occupancy, supply and demand, asset quality, financing availability, and investor expectations all matter.
For investors, owners, and business operators, the best approach is to evaluate the real estate and financing together.
That is especially important when buying, selling, or refinancing commercial property in Katy, Fulshear, West Houston, and the Greater Houston market.
Bill Rapp, CCIM
eXp Commercial — Viking Enterprise Team
📍 Serving Katy | Fulshear | Richmond | Brookshire | West Houston | Greater Houston
📧 [email protected]
☎️ 281-222-0433
🌐 HoustonRealEstateBrokerage.com
📍 eXp Commercial & eXp Realty
📅 Calendly.com/VikingEnterprise
https://www.houstonrealestatebrokerage.com/
https://www.houstonrealestatebrokerage.com/houston-cre-navigator
https://www.commercialexchange.com/agent/653bf5593e3a3e1dcec275a6
http://expressoffers.com/[email protected]
https://app.bullpenre.com/profile/1742476177701x437444415125976000
https://author.billrapponline.com/
https://www.amazon.com/dp/B0F32Z5BH2
https://veed.cello.so/FOmzTty6oi9
https://buymeacoffee.com/vikingente3
https://creplaybookseries.billrapponline.com
https://creplaybook.billrapponline.com/
© Bill Rapp, Broker Associate, eXp Commercial Viking Enterprise Team
Commercial Real Estate Advisors Serving Katy, Fulshear & Greater Houston
Helping Property Owners, Investors & Businesses Make Smarter Commercial Real Estate Decisions
Whether you're buying, selling, leasing, investing, or financing commercial real estate, having the right advisor can make all the difference.
At eXp Commercial – Viking Enterprise Team, we provide comprehensive commercial real estate brokerage and advisory services for property owners, investors, developers, landlords, tenants, and business owners throughout Katy, Fulshear, Houston, and the surrounding Texas markets.
Our team combines local market expertise with commercial investment knowledge and capital markets experience to help clients maximize property value, identify new opportunities, reduce risk, and achieve long-term investment success.
From a single office building to a growing investment portfolio, we provide strategic guidance from acquisition through disposition.
Comprehensive Commercial Real Estate Services
Commercial Property Sales
Selling commercial real estate requires far more than placing a property on the market. We develop customized marketing strategies designed to maximize exposure while targeting qualified buyers locally, regionally, and nationally.
Our services include:
Property valuation and pricing strategy
Investment analysis
Professional marketing campaigns
Buyer qualification
Contract negotiation
Due diligence coordination
Transaction management through closing
Whether you're selling office, retail, industrial, multifamily, land, medical, mixed-use, or investment property, our objective is simple—maximize your property's value while creating a smooth transaction.
Commercial Leasing Services
Vacancies reduce cash flow and impact property performance.
We help landlords lease available space by creating effective marketing campaigns, identifying qualified tenants, negotiating favorable lease terms, and minimizing downtime.
Our leasing services include:
Office leasing
Retail leasing
Industrial leasing
Medical office leasing
Flex space leasing
Warehouse leasing
Landlord representation
Tenant representation
Lease renewals
Lease negotiations
Our goal is to keep your property occupied with quality tenants while protecting your long-term investment.
Commercial Property Acquisitions
Whether you're purchasing your first commercial property or expanding a large investment portfolio, we help identify opportunities that align with your investment objectives.
Our acquisition services include:
Market research
Property sourcing
Financial analysis
Cap rate evaluation
Cash flow analysis
Due diligence
Negotiation
Closing coordination
We help investors make informed decisions backed by market data and financial analysis—not emotion.
Investment Property Analysis
Every investment should begin with a thorough understanding of risk and return.
We assist investors by evaluating:
Net Operating Income (NOI)
Capitalization Rates
Cash-on-Cash Returns
Internal Rate of Return (IRR)
Market Rent Analysis
Occupancy Trends
Comparable Sales
Exit Strategies
Our investment analysis helps clients make data-driven decisions before committing capital.
Commercial Financing & Capital Advisory
One of the biggest advantages of working with Viking Enterprise Team is access to commercial financing expertise.
Through our capital markets relationships, we help clients evaluate financing options for acquisitions, refinancing, construction, bridge financing, SBA loans, investment properties, and owner-occupied commercial real estate.
We help clients:
Evaluate financing options
Analyze refinancing opportunities
Improve loan positioning
Understand lender requirements
Coordinate with commercial lenders
Structure financing strategies
Real estate and financing should work together—not independently.
Portfolio Growth & Investment Strategy
Building long-term wealth through commercial real estate requires strategic planning.
We work with investors to:
Expand investment portfolios
Identify off-market opportunities
Improve portfolio performance
Evaluate redevelopment opportunities
Reposition underperforming assets
Develop long-term acquisition strategies
Whether you're purchasing your second investment or your fiftieth, we help create a roadmap for continued growth.
Landlord Representation
Commercial property owners face constant challenges:
Tenant turnover
Lease negotiations
Rental rates
Market competition
Property positioning
We provide landlord representation focused on maximizing occupancy, improving lease terms, increasing property value, and strengthening long-term cash flow.
Tenant Representation
Businesses often outgrow their current space or need a location that better supports future growth.
We represent tenants throughout the site selection process, helping negotiate favorable lease terms while identifying properties that fit operational and financial objectives.
Our tenant services include:
Office space
Retail locations
Industrial facilities
Warehouse space
Medical offices
Flex properties
Build-to-suit opportunities
Market Analysis & Commercial Consulting
Successful commercial real estate decisions begin with accurate market intelligence.
Our advisory services include:
Market studies
Property positioning
Rent analysis
Development feasibility
Redevelopment analysis
Demographic research
Growth corridor identification
Competitive property analysis
Whether you're considering selling today or planning five years ahead, we help you understand where the market is headed.
Joint Ventures & Investment Partnerships
Many commercial opportunities require additional equity, strategic partners, or experienced investors.
We help facilitate introductions between qualified investors, developers, operators, and commercial property owners seeking partnership opportunities for acquisitions, development, redevelopment, or recapitalization.
Exit Planning & Wealth Preservation
Every commercial investment eventually reaches a transition point.
Whether you're considering:
Selling
Refinancing
Recapitalizing
Completing a 1031 Exchange
Passing assets to the next generation
Repositioning your portfolio
we help create an exit strategy that aligns with your financial goals while maximizing value and minimizing unnecessary risk.
Why Choose Viking Enterprise Team?
Commercial real estate is about more than buying and selling properties—it's about creating long-term value.
Our clients benefit from:
Local expertise throughout Katy, Fulshear, Houston, and surrounding markets
Experience representing investors, developers, business owners, landlords, and tenants
Comprehensive brokerage and advisory services
Commercial financing insight and capital markets knowledge
Investment-focused analysis
Strategic negotiation
Professional marketing
Personalized service from initial consultation through closing
We believe informed clients make better decisions, and our role is to provide the expertise, market intelligence, and guidance needed to help you succeed.
Let's Discuss Your Commercial Real Estate Goals
Whether you're buying, selling, leasing, investing, refinancing, or planning your next commercial real estate transaction, Viking Enterprise Team is ready to help.
Schedule a confidential consultation to discuss your objectives and discover how our experience, market knowledge, and strategic approach can help you maximize the value of your commercial real estate investments.
Contact eXp Commercial – Viking Enterprise Team today and let's build your commercial real estate strategy together.
Find the perfect location for your business.
Let us help your business succeed.
🏢 How Commercial Real Estate Interest Rates Affect Property Values: What Investors Need to Know 📈
🏢 How Commercial Real Estate Interest Rates Affect Property Values: What Investors Need to Know 📈
💰 Interest Rates vs. Commercial Property Values: Why Higher Rates Can Push CRE Prices Down 🏙️
________________________________________________________________________________
How Commercial Real Estate Interest Rates Affect Property Values
Interest rates are one of the most important forces influencing commercial real estate values. When rates move, the impact extends far beyond the monthly mortgage payment.
Higher borrowing costs can reduce investor returns, constrain loan proceeds, influence cap rates, and ultimately change what buyers are willing—or able—to pay for a property.
But the relationship is not as simple as rates go up, property values go down.
Net operating income, rent growth, supply and demand, occupancy, investor expectations, lender underwriting, and the availability of capital all play a role.
For commercial real estate investors and business owners, understanding these relationships can help you make better acquisition, disposition, refinancing, and financing decisions.
Why Interest Rates Matter in Commercial Real Estate
Most commercial real estate transactions involve leverage.
If an investor purchases a $5 million property, they may finance 60% to 75% of the acquisition. When the interest rate on that debt increases, the property's annual debt service generally increases as well.
That can create several consequences:
·Lower cash flow after debt service
·Lower cash-on-cash returns
·Reduced debt-service coverage
·Lower maximum loan proceeds
·Greater equity requirements
·Pressure on the price a leveraged buyer can afford to pay
This is why financing conditions and property valuations are closely connected.
The Connection Between Interest Rates and Cap Rates
Commercial real estate is frequently valued using the capitalization rate:
Property Value = Net Operating Income ÷ Cap Rate
Assume a property produces $500,000 of annual NOI.
At a 5% cap rate, the indicated value is:
$500,000 ÷ 5% = $10,000,000
At a 6% cap rate, the indicated value becomes:
$500,000 ÷ 6% = $8,333,333
At a 7% cap rate, it falls to approximately:
$500,000 ÷ 7% = $7,142,857
That illustrates why relatively small changes in cap rates can create significant changes in property valuations.
Interest rates and cap rates do not move in perfect lockstep, but higher borrowing costs can contribute to upward pressure on cap rates as investors demand sufficient returns relative to their cost of capital and alternative investments.
Higher Rates Can Reduce Loan Proceeds
One of the most overlooked effects of higher interest rates is their impact on commercial loan sizing.
A lender might advertise a maximum 70% loan-to-value ratio, but that does not automatically mean a borrower will receive 70% financing.
Commercial loans can also be constrained by debt-service coverage ratio (DSCR) and debt yield requirements.
When interest rates rise, the same loan amount produces higher debt service. If NOI does not increase sufficiently, the property's DSCR declines.
The lender may therefore reduce the loan amount.
That means an investor who expected 30% equity could suddenly need 35%, 40%, or more.
Why Buyers May Lower Their Offers
Consider a buyer evaluating a commercial investment.
If financing becomes more expensive while rents and NOI remain unchanged, the buyer may face a lower leveraged return.
The buyer essentially has several choices:
Pay more equity.
Accept a lower return.
Obtain better financing.
Increase the property's income.
Pay a lower purchase price.
That final option is one reason higher rates can place downward pressure on commercial property values.
The Refinancing Problem
Interest rates also affect owners who are not selling.
Commercial real estate loans commonly have maturities that are shorter than their amortization periods. An investor could have a loan amortized over 25 years but maturing after five, seven, or ten years.
At maturity, the remaining balance generally needs to be refinanced or paid off.
Suppose an owner financed a property when rates were substantially lower. When the loan matures, the replacement loan could have significantly higher debt service.
The property may no longer support the same loan balance under the lender's DSCR requirements.
This can create a refinancing gap.
The owner may need to contribute additional equity, restructure the financing, improve NOI, extend the existing debt, or sell the property.
Interest Rates Are Only Part of the Valuation Equation
A common mistake is assuming interest rates alone determine commercial property values.
They do not.
Consider a property where rents are increasing rapidly and occupancy is strong. NOI could increase enough to partially or fully offset cap-rate expansion.
For example, a property generating $500,000 of NOI at a 5% cap rate is worth $10 million.
If NOI grows to $600,000 and the market cap rate expands to 6%, the indicated value is still:
$600,000 ÷ 6% = $10,000,000
The cap rate increased, but the higher income offset the impact.
This is why investors should focus on both sides of the equation: income and valuation multiples.
Not Every Property Type Reacts the Same Way
Interest-rate sensitivity can also differ across property types and markets.
A fully leased industrial property with strong rent growth and a credit tenant may respond differently than an older office building with substantial vacancy.
Similarly, a well-located retail center with below-market rents could offer significant NOI growth potential despite a higher-rate environment.
Investors should evaluate factors such as tenant credit, lease rollover, rent growth, vacancy, capital expenditures, market supply, replacement cost, location, and future NOI—not rates alone.
Higher Interest Rates Can Create Opportunities
Higher rates are not automatically bad for commercial real estate investors.
They can reduce competition from highly leveraged buyers and create opportunities for investors with available capital.
A higher-rate environment may also produce:
·More motivated sellers
·Better acquisition pricing
·Seller-financing opportunities
·Assumable debt opportunities
·Preferred-equity structures
·Value-add acquisitions
·Refinancing opportunities when rates eventually improve
The key is underwriting the investment based on realistic financing assumptions rather than assuming yesterday's capital markets will return tomorrow.
What Investors Should Stress-Test
Before acquiring or refinancing commercial real estate, investors should model multiple scenarios.
Instead of asking only, “What is my interest rate today?”, ask what happens if the property's financial assumptions change.
For example:
What happens if the refinance rate is 1% or 2% higher?
What happens if the lender requires a higher DSCR?
What happens if the exit cap rate increases?
What happens if NOI falls 10%?
What happens if the property requires more equity at refinancing?
Sophisticated underwriting should consider both the property risk and capital-market risk.
What Business Owners Should Know
Interest rates matter for owner-occupied commercial real estate as well.
A business purchasing an office, warehouse, medical facility, retail property, or other operating location should evaluate more than the purchase price.
Financing structure can materially affect occupancy costs and cash flow.
Depending on the transaction, conventional commercial financing, SBA financing, construction financing, or other structures may produce very different results.
The right question is not simply:
“What is the lowest rate?”
It is:
“Which financing and real estate structure best supports the business?”
The Bottom Line
Commercial real estate interest rates can affect property values through several channels simultaneously.
Higher rates can increase debt service, reduce DSCR, constrain loan proceeds, increase required equity, lower leveraged returns, and put upward pressure on cap rates.
But interest rates do not determine value in isolation.
NOI, rent growth, occupancy, supply and demand, asset quality, financing availability, and investor expectations all matter.
For investors, owners, and business operators, the best approach is to evaluate the real estate and financing together.
That is especially important when buying, selling, or refinancing commercial property in Katy, Fulshear, West Houston, and the Greater Houston market.
Bill Rapp, CCIM
eXp Commercial — Viking Enterprise Team
📍 Serving Katy | Fulshear | Richmond | Brookshire | West Houston | Greater Houston
📧 [email protected]
☎️ 281-222-0433
🌐 HoustonRealEstateBrokerage.com
📍 eXp Commercial & eXp Realty
📅 Calendly.com/VikingEnterprise
https://www.houstonrealestatebrokerage.com/
https://www.houstonrealestatebrokerage.com/houston-cre-navigator
https://www.commercialexchange.com/agent/653bf5593e3a3e1dcec275a6
http://expressoffers.com/[email protected]
https://app.bullpenre.com/profile/1742476177701x437444415125976000
https://author.billrapponline.com/
https://www.amazon.com/dp/B0F32Z5BH2
https://veed.cello.so/FOmzTty6oi9
https://buymeacoffee.com/vikingente3
https://creplaybookseries.billrapponline.com
https://creplaybook.billrapponline.com/
© Bill Rapp, Broker Associate, eXp Commercial Viking Enterprise Team
Find the perfect location for your business.
Let us help your business succeed.

Sign up to receive the latest news on property investment and commercial real estate listings.
9600 Great Hills Trail, Suite 150w Austin, TX 78759 |
855.450.0324 xx255
Texas Real Estate Commission Consumer Protection Notice Texas Real Estate Commission
Information About Brokerage Services eXp Commercial LLC #9010212
Viking Enterprise LLC #9009614

Sign up to receive the latest news on property investment and commercial real estate listings.


Contact Us
901 S Mopac Expwy, Bldg 2, Suite 350 Austin, TX 78746 | 512.474.5557Texas Real Estate Commission
Consumer Protection Notice Texas Real Estate Commission Information About Brokerage Services Reliance Retail, LLC #603091
Texas RS, LLC #9003193 | RESOLUT RE Is Licensed In Louisiana #0995694083
Facebook
Instagram
X
LinkedIn
Youtube
TikTok